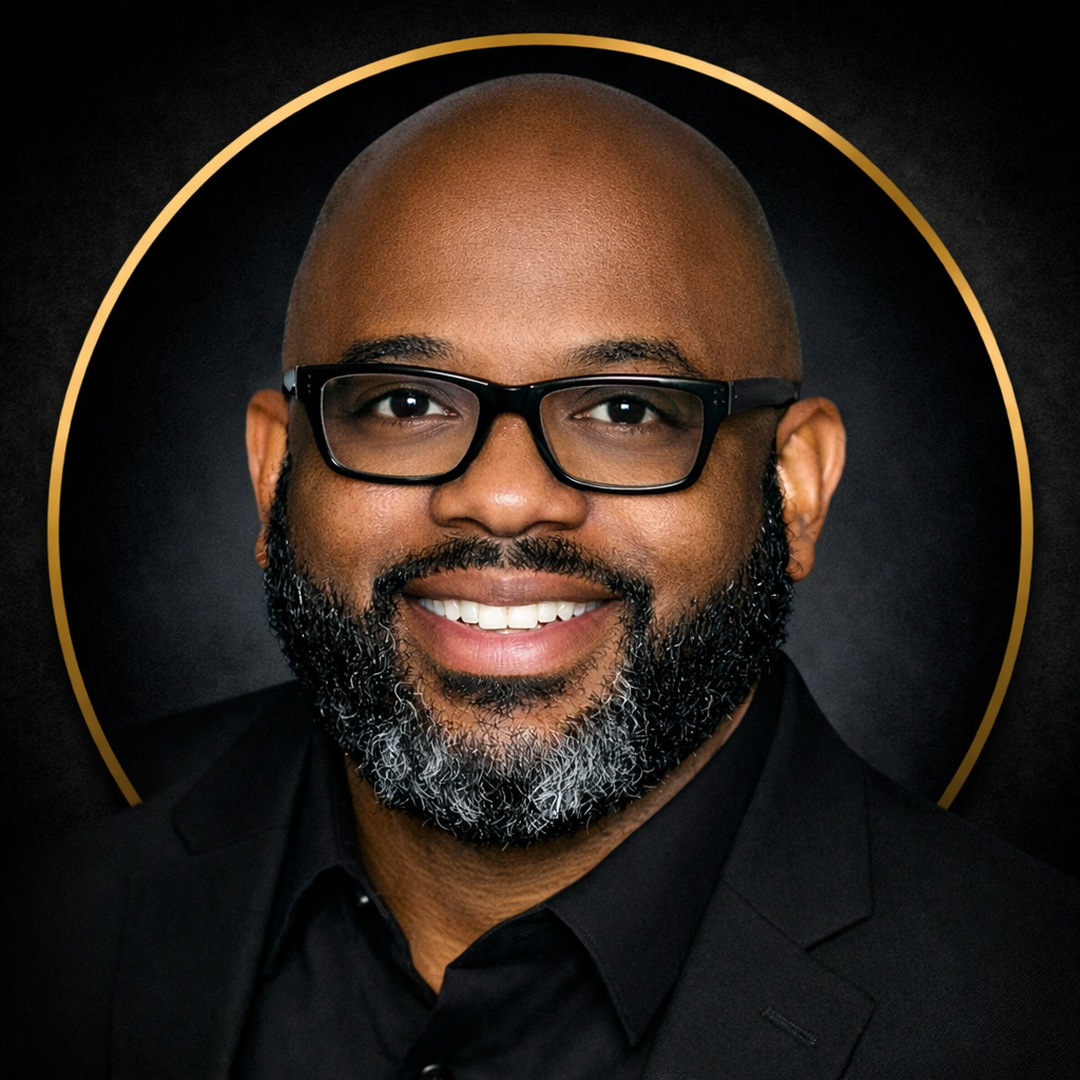
If you're 62 or older and have significant equity in your Tennessee home, a HECM reverse mortgage may let you access that equity without a monthly mortgage payment. I'm Trevor Forbes, a Memphis-area mortgage loan officer, and I sit down with you face to face — at your kitchen table if you prefer — from the first conversation through signing your documents.
As a broker, I work with some of the top reverse mortgage lenders in the country. You get national lending strength, and a local person you can actually sit across the table from.
Most reverse mortgage companies do everything by phone from out of state. Trevor comes to you. Invite your adult children or a trusted advisor to sit in — questions are welcome.
Book an In-Home ConsultationNot ready yet? See what affects your numbers →
Reverse mortgages are a big decision, usually about the home you've spent decades paying for. Many homeowners are contacted by national companies that handle everything over the phone. There's nothing wrong with national lenders — I work with some of the best in the country. The difference is who sits across the table from you.
I'm local, right here in the Memphis area. I've spent more than 30 years advising clients on their finances, I studied at Austin Peay State University, and I hold a degree in finance — so I look at a reverse mortgage the way a retirement advisor would: cash flow, what it does for your plan, and what it leaves for your family.
I'll never pressure you. My job is to lay out the options side by side — reverse mortgage, HELOC, selling and downsizing, or doing nothing — so you and your family can decide with clear numbers. Compare reverse mortgage vs. HELOC →
A HECM (Home Equity Conversion Mortgage) is a reverse mortgage insured by the FHA, available nationwide to eligible homeowners 62 and older. Tennessee homeowners have an added layer of protection: the state's own Home Equity Conversion Mortgage Act, which reinforces the federal counseling requirement and helps make sure Tennessee seniors work only with vetted, HUD-approved lenders before committing to anything.
Instead of you paying the lender each month, eligible proceeds can flow to you — as a line of credit, monthly advances, a lump sum, or a combination — while you continue living in the home as your primary residence and stay current on property taxes, homeowners insurance, and basic upkeep.
Because I work with multiple top reverse lenders, I can match the program to your home and your goals instead of fitting you into one company's product.
Program availability, age minimums, and terms vary by lender and are subject to underwriting. Proprietary (non-HECM) reverse mortgages are not FHA-insured.
How much equity may be available generally depends on your age (older borrowers can typically access more), your home's appraised value, current interest rates, and the specific loan program. If you still owe money on your home, that balance is generally paid off first at closing. See the factors behind your estimate →
Federal law requires an independent counseling session with a HUD-approved counselor before any HECM application can move forward — and Tennessee's HECM Act reinforces this at the state level. The counselor doesn't work for Trevor, NEXA Mortgage, or any lender.
Sessions are typically done by phone, take about an hour, and produce a certificate valid for 180 days. Tennessee does not require in-person counseling. Call for a referral to a HUD-approved counselor serving Tennessee.
HUD's official counselor search is also available directly at hud.gov/program_offices/housing/sfh/hcc/hcc_home.
You retain title to your home throughout the loan. When the loan becomes due — typically when the last borrower sells, permanently moves out, or passes away — your heirs generally have options: repay the loan and keep the home, sell the home and keep any remaining equity, or walk away with no further obligation. HECM loans are non-recourse, meaning heirs will never owe more than the home is worth at repayment, regardless of the loan balance. Adult children are always welcome at our meetings.
I meet face to face with homeowners in Memphis, Germantown, Collierville, Cordova, Bartlett, Arlington, Lakeland, and across Shelby County. Homeowners elsewhere in Tennessee — Nashville, Knoxville, Chattanooga, Murfreesboro, Jackson — can work with me too; call and we'll set up the best way to meet. Reverse mortgage rules, HUD counseling requirements, and Tennessee's HECM Act apply the same way wherever you live in the state.
Trevor meets homeowners 62+ in person across Memphis, Germantown, Collierville, Cordova and Bartlett, including signing documents at your kitchen table. Start with the guide that fits your situation.
A local loan officer, some of the top reverse lenders in the country, and no pressure. Bring your questions — and your family.
No obligation · No hard sell · Just clarity on what's possible for you.